— News Center
National Construction Steel Prices Expected to Fluctuate Narrowly on November 13
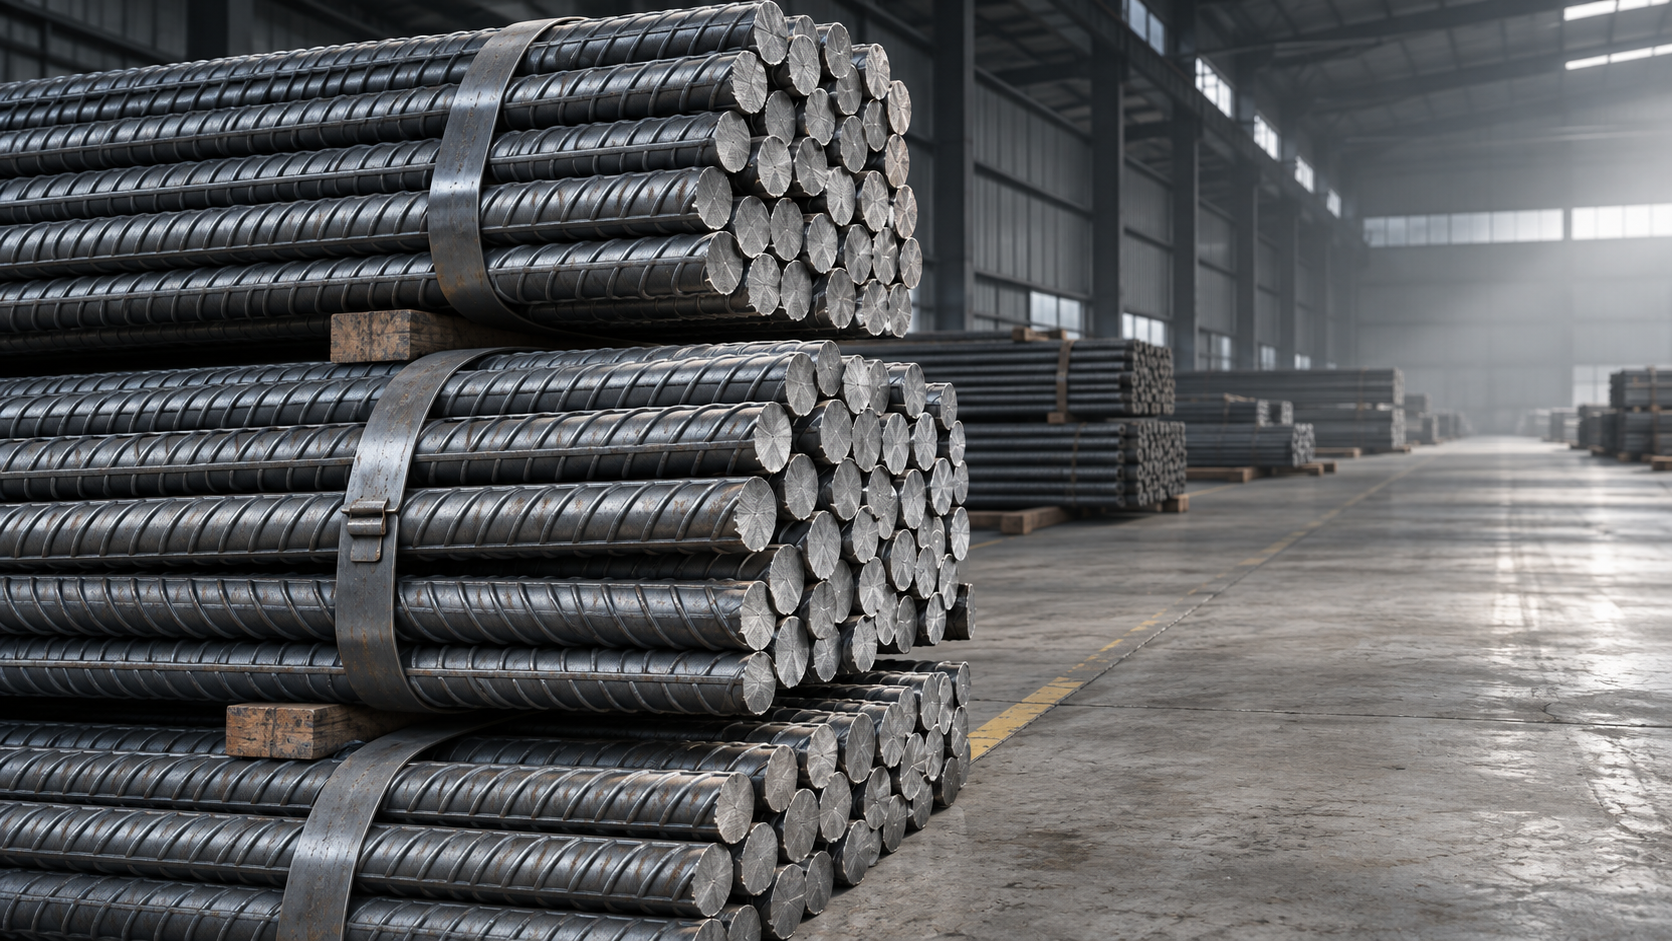
On November 12, 2026, the national construction steel market recorded a further decline in the average price of grade III earthquake-resistant rebar, while the main rebar futures contract closed at 3,030 yuan per tonne. A November 13 morning report from Mysteel expects prices to fluctuate within a narrow range as low inventories support prices and weaker coke costs and seasonal demand changes pull in the other direction. The update may influence purchasing, trading and delivery decisions, but the supplied information does not identify a new policy, regulation, standard or trade rule.
Rebar prices edge lower as inventory and cost signals diverge
According to the November 13 morning report, the national average price of grade III earthquake-resistant rebar stood at 3,297 yuan per tonne on November 12, down 5 yuan per tonne from the previous day. The main rebar futures contract closed at 3,030 yuan per tonne.
The report identifies low inventories and continued inventory reduction as support for the lower end of prices. It also cites a proposed reduction in coke prices as a factor weakening cost support, alongside seasonal changes in demand. On that basis, it expects national construction steel prices to fluctuate within a narrow range on November 13.
Where the price signals may affect steel transactions
Purchasers weighing order timing
Analysis suggests that buyers of construction steel may need to balance the prospect of modest price movements against the availability of the products they actually require. A national average provides a reference point, but it does not establish the price, stock position or delivery terms for a particular order. Buyers considering a purchase could therefore compare current supplier quotations with their project schedules and specifications before deciding whether to place an order or wait.
The inventory signal deserves particular attention. Low inventories may support prices, but the supplied summary does not say whether a specific grade or quantity is available from any supplier. A purchaser seeking grade III earthquake-resistant rebar could check availability and delivery dates directly, rather than treating the national inventory assessment as confirmation of supply for an individual project.
Traders managing quotations and stock
For traders and distribution businesses, the combination of inventory reduction and weaker cost support may complicate quotation decisions. Analysis suggests that a seller holding stock may face a different commercial position from one arranging supply after receiving an order. The expected narrow trading range is a forecast, so it does not guarantee that an individual transaction will remain within any particular price band.
Traders could review the period for which a quotation remains valid, the product and quantity covered, and the delivery terms agreed with each customer. Such checks would help both parties understand how a transaction relates to the market reference. They are commercial precautions, not new obligations announced by the report.
Contractors coordinating material deliveries
Construction contractors may be affected through the timing and cost of material purchases. From an industry perspective, seasonal changes in demand could make it useful to compare expected site requirements with planned delivery dates. If a project’s needs change, the quantity or timing of an order may also need review; the input does not establish that any particular project has changed its schedule.
Contractors could confirm that purchase documents describe the required product and that proposed delivery arrangements fit the project’s needs. The mention of earthquake-resistant rebar identifies the product in the reported average; it does not announce a change to a technical standard, certification requirement or acceptance procedure.
Suppliers assessing the cost signal
The proposed coke price reduction is relevant to the report’s assessment of cost support. Analysis suggests that suppliers may wish to consider whether changes in input costs are reflected in their own quotations and purchasing discussions. The information provided does not establish that a reduction has taken effect, quantify its size or show how it would affect the costs of any individual supplier.
For that reason, a proposed change in coke prices should not be treated as a confirmed change in the price of finished construction steel. Actual offers may reflect several considerations, including product availability and delivery arrangements. Businesses can assess those offers on their stated terms while continuing to monitor whether the proposed cost change is implemented.
Practical checks for the next purchasing cycle
Separate reference prices from executable offers
The reported average of 3,297 yuan per tonne and the futures close of 3,030 yuan per tonne describe different market references. Analysis suggests that neither figure alone establishes the price payable under a specific physical supply contract. Buyers and sellers could record which product, quantity and delivery terms a quotation covers, then compare offers on a consistent basis.
Where a commercial agreement refers to a market price, the parties may also wish to verify the reference and timing stated in their own documents. The supplied report does not prescribe a pricing formula or change existing contractual terms. Any adjustment would depend on the agreement and the parties’ subsequent arrangements.
Test inventory assumptions against actual needs
The report describes low inventories and continued inventory reduction as supporting the price floor. For an individual buyer, the practical question is whether the necessary steel can be supplied when needed. An appropriate check may include the requested grade, order volume and proposed delivery date, followed by confirmation with the supplier.
Analysis suggests that waiting for a lower price could carry a different operational trade-off from securing an offer that fits a project schedule. The available information does not establish which choice would be more economical. A staged purchasing plan, if consistent with the buyer’s circumstances and contract, is one option to assess rather than a measure required by the report.
Follow the proposed coke price adjustment
The cost signal remains conditional because the input describes a proposed reduction in coke prices. Market participants could watch for reliable subsequent information on whether that proposal takes effect and how suppliers describe its relevance to their offers. They should also distinguish an announced or proposed adjustment from a change reflected in an agreed transaction.
Even if coke prices fall, the effect on construction steel prices cannot be determined from the supplied figures alone. Inventory levels and seasonal demand are also part of the reported assessment. Analysis therefore supports monitoring these signals together rather than assuming that one input will determine the next quotation.
Keep product and delivery documents aligned
Businesses may use the market update as a prompt to check that quotations, purchase orders and delivery arrangements describe the same product and commercial terms. For buyers of earthquake-resistant rebar, that may include confirming the requested grade and any project-specific documentation with the supplier before an order is finalized.
This is a verification step based on ordinary transaction needs, not evidence of a newly introduced certification or testing rule. If a project has applicable technical or acceptance requirements, the parties should consult the documents governing that project. The supplied summary does not identify any change to those requirements.
A market forecast, with no rule change established
Editorial analysis indicates that the November 13 update is best understood as a short-term market assessment. It reports a price movement, a futures close and the factors behind an expectation of narrow price fluctuations. It does not identify a policy announcement, regulatory action, revised standard, certification decision or change in trade rules.
That distinction matters for interpreting the possible business response. A forecast can inform a purchasing discussion, but it does not itself alter a contract or create a compliance deadline. Similarly, the reported product category should not be read as evidence that the rules governing that product have changed. Any such development would need separate verification from the relevant source.
What deserves closer attention is whether later information supports the report’s assessment of inventories, coke costs and demand. If inventory reduction continues, its effect on available offers may warrant review; if the proposed coke adjustment is implemented, participants may also examine how sellers respond. These are possibilities for observation, not outcomes established by the November 12 figures.
The relationship between the national average and actual transactions also remains an open question for each business. A national figure can support comparison over time, while an individual purchase depends on the offer and terms available to the parties. Market feedback and subsequent quotations may therefore be more useful for a specific decision than assuming that every transaction follows the same path.
Using the forecast in commercial decisions
The immediate significance of the update lies in the balance it describes: low inventories and continued stock reduction support prices, while a proposed coke price cut and seasonal demand changes complicate the outlook. The stated expectation of narrow fluctuations is useful context for purchasers, traders and contractors, but it remains a forecast for November 13 rather than a guaranteed result.
A measured response is to check current quotations, product availability and delivery needs against the terms of each transaction, while monitoring later information on the factors identified in the report. The update should be handled as a market signal requiring continued observation; it should not be presented as a confirmed change in regulation, certification or trade practice.
Basis of this report and points to verify
This article is based on the user-provided news title, event date and event summary, which attribute the market figures and forecast to Mysteel’s November 13 morning report. No specific official source link was provided in the input, and the underlying information should continue to be verified. Subsequent industry reporting and, where relevant, official announcements or applicable project documents may help establish whether market conditions, purchasing terms or any actual rules have changed.
Further observation should focus on inventory movements, the status of the proposed coke price reduction, seasonal demand, supplier quotations and industry feedback. If a policy, standard, certification or tender requirement is later reported to have changed, its details and application should be checked against the relevant primary document before businesses treat it as an operative requirement.
By clicking 'Allow All', you agree to the storage of cookies on your device to enhance site navigation, analyze site usage and assist with our marketing efforts.
Leave a message and we'll get back to you soon.